By Carla Calleja, MBA, REB
The story: a family that checked its bills twice this week
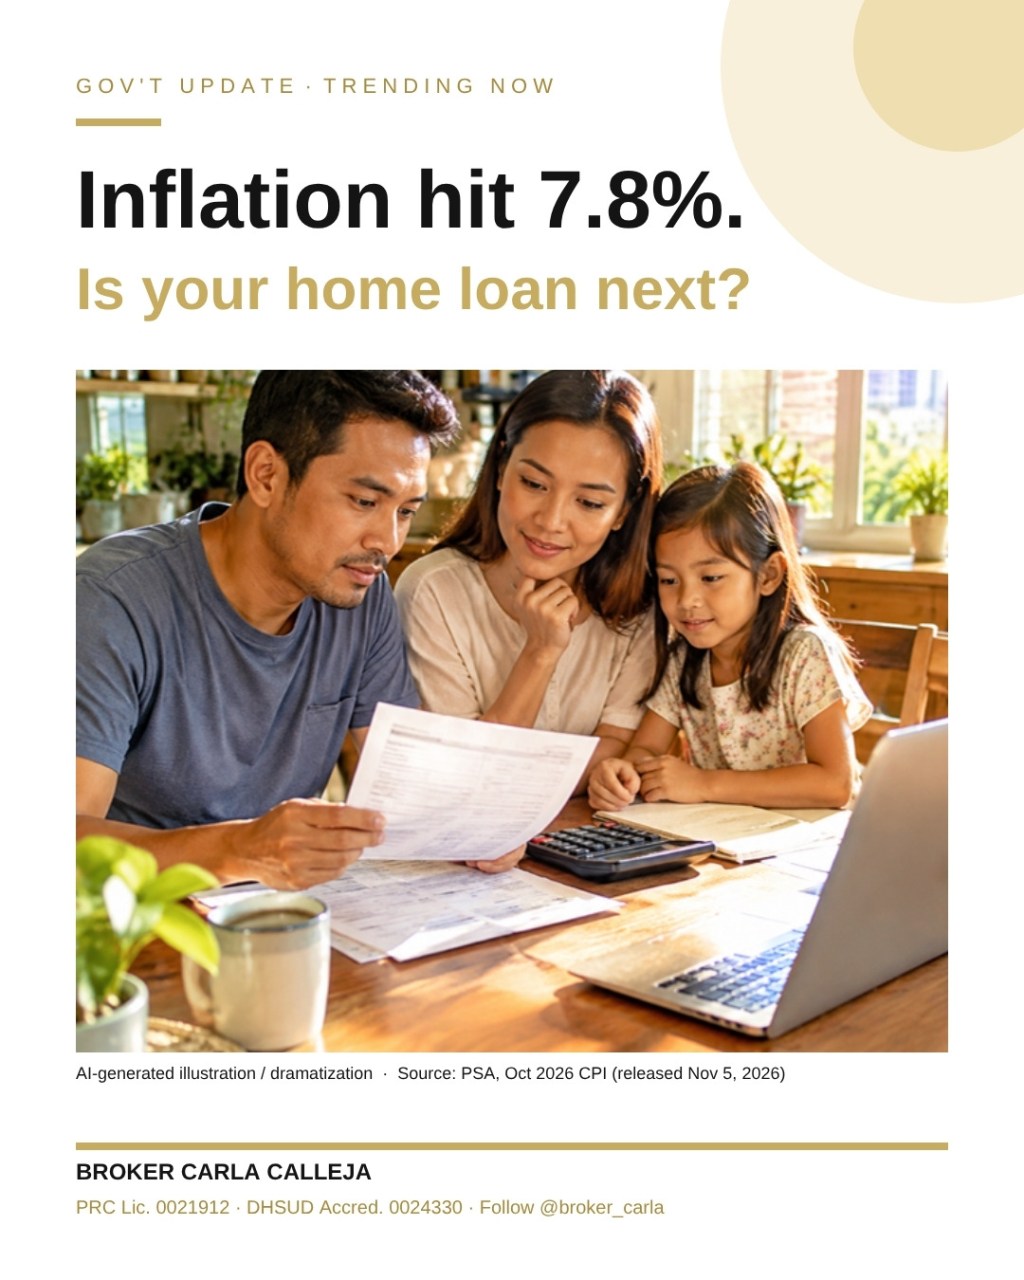
Picture a young family in Parañaque. Their condo loan reprices next year, their electric bill went up again, and their lease on a second unit they rent out is up for renewal in January. On Thursday the news said inflation jumped to 7.8%. Their first question to me was simple: “Broker Carla, tataas ba ang hulog namin?”
The short answer
Inflation does not change your loan rate overnight. But it raises the odds that interest rates stay high for longer, and it squeezes the budgets of everyone in a property deal: borrowers, tenants, landlords, buyers and sellers. The time to prepare is before your repricing date or lease renewal, not after.
What changed
- The Philippine Statistics Authority reported that headline inflation rose to 7.8% in October 2026, from 7.2% in September.
- The index for housing, water, electricity, gas and other fuels rose to 9.3%, from 8.4%.
- Transport inflation jumped to 20.1%, from 14.6%, on higher fuel prices and fares.
- The Bangko Sentral ng Pilipinas has already raised its policy rate to 5.50%. It said October’s figure was within its 7.1% to 8.1% forecast range and that it will stay vigilant as it assesses new data.
I wrote about the BSP’s rate hike last month in BSP Hiked Rates to 5.50%: Will Your Home Loan Go Up? Today’s numbers are the reason that story matters.
Who is affected
- Borrowers whose bank or Pag-IBIG loan rate reprices in the coming months. A new rate is usually set at repricing based on market conditions at that time.
- Tenants and landlords. Higher utility costs hit tenants first. Landlords feel it at renewal time, when tenants push back on increases.
- Buyers and OFWs budgeting a monthly amortization. A higher rate means a lower loan amount for the same monthly budget.
- Sellers and heirs. When borrowing costs more, buyers take longer and negotiate harder. Pricing right matters more.
What to do now: step by step
- Find your repricing date. It is in your loan agreement or disclosure statement. Ask your bank, in writing, what options you have before that date, including fixing the rate for a longer period.
- Compare before you sign. If you are buying, compare Pag-IBIG and bank offers on the same loan amount and term. Look at the fixing period, not only the starting rate.
- Landlords and tenants: read the lease. Follow the escalation clause you agreed on. Put any renewal terms in writing, signed by both sides.
- Build a buffer. Keep cash for a few months of amortization or rent, especially if your income is variable.
- Sellers: price with today’s buyer in mind. Ask your broker for recent comparable sales, not old asking prices.
What this means for you: checklist
- Loan agreement and latest statement of account
- Your repricing date, written on your calendar
- Lease contract with the escalation clause highlighted
- Updated monthly budget with utilities at current rates
- For sellers: a fresh comparative market analysis
FAQ
Will my fixed-rate loan change right away?
Not during the fixed period stated in your contract. The change usually comes at repricing.
Can my landlord raise the rent because of inflation?
Only as allowed by your lease and the law that applies to your unit. Increases are usually discussed at renewal. Check your contract first.
Should I wait to buy until rates go down?
Nobody can time rates. If the property, price and monthly payment work for your budget today, with a buffer, waiting may cost you the right unit. If they don’t, waiting is fine.
Is property still a hedge against inflation?
Over long periods, well-located property has historically held value, but it is not guaranteed and it is not liquid. Buy for need and cash flow, not for headlines.
Ask Broker Carla
May tanong ka rin? Comment RATE on my posts, send me your “Broker Carla, …” question on facebook.com/carlacallejabrokerphilippines, or email buyrentph@gmail.com.
This article is for general information only and is not legal or tax advice. For your specific situation, consult a lawyer or a licensed professional.

